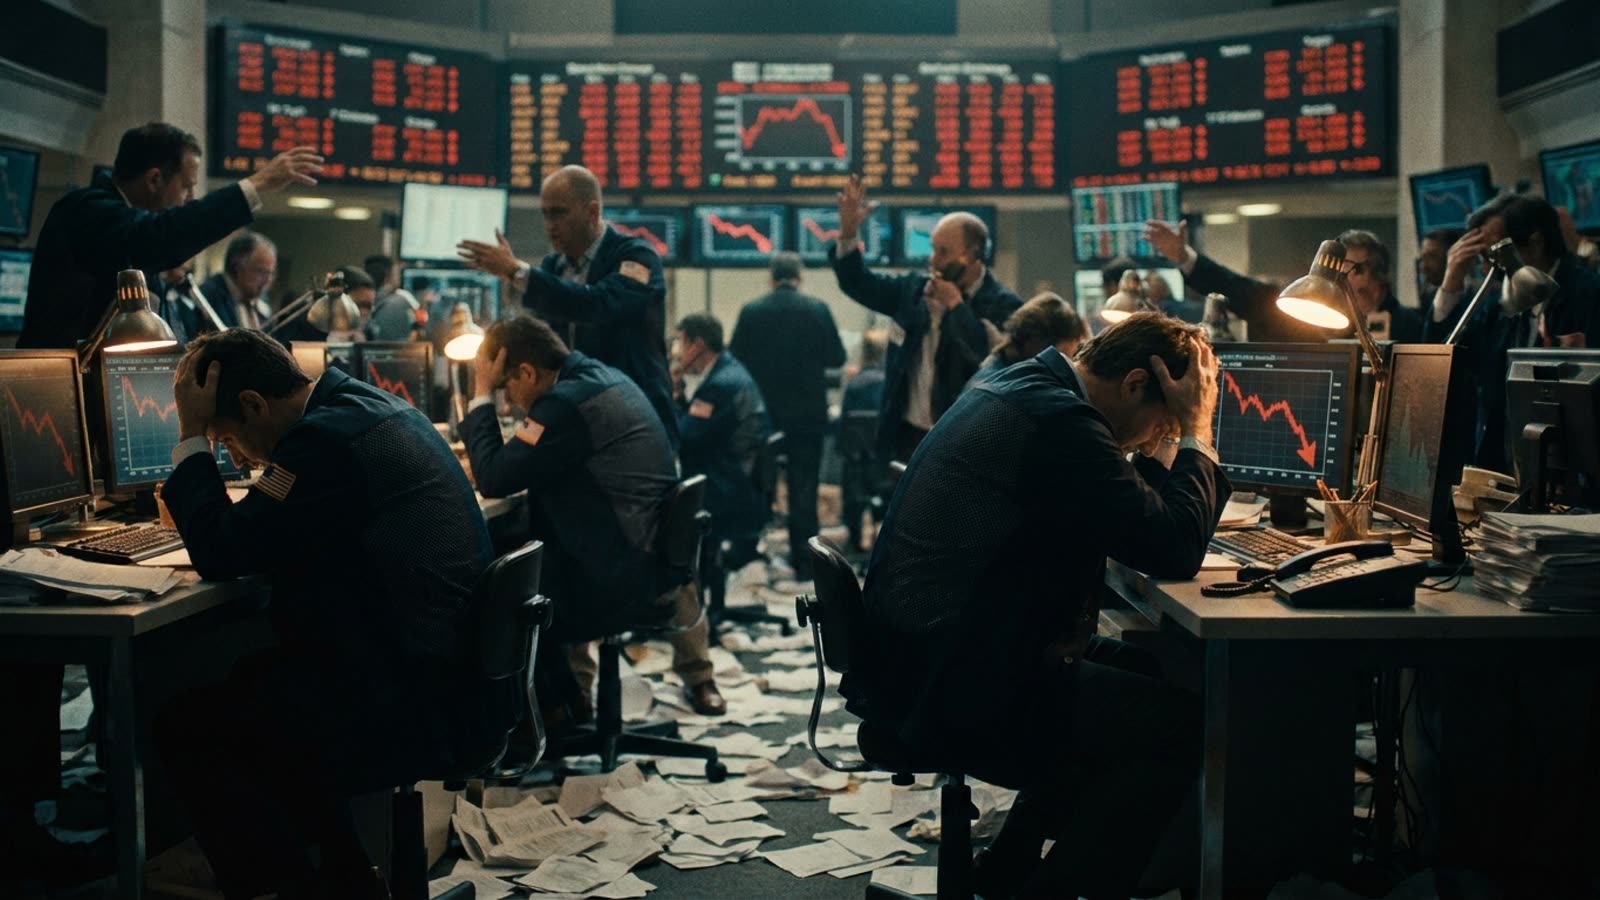
For two years, the investment thesis was simple: pour money into anything adjacent to artificial intelligence and watch it compound. That thesis cracked on Thursday as global equity markets suffered their sharpest coordinated decline since the regional banking panic of 2023, with semiconductor stocks leading the carnage and South Korea's Kospi index plunging 8% in a single session.
The proximate cause is familiar—persistent inflation data that has pushed the probability of an October Federal Reserve rate hike to 29%, up from 18% a week ago. But the deeper driver is a question that has lurked beneath the AI euphoria for months: can the staggering capital expenditure required to train and deploy large language models ever generate commensurate returns?
The chipmaker contagion
Samsung, ASML, and their peers across Asia and Europe bore the brunt of Thursday's rout. These companies have been valued not on current earnings but on the assumption of perpetually expanding AI infrastructure budgets from hyperscalers like Microsoft, Google, and Amazon. When bond yields rise and capital becomes more expensive, that assumption deserves scrutiny. Investors are now providing it, aggressively.
SoftBank, which has staked its post-WeWork rehabilitation on AI bets, fell sharply in Tokyo trading. The message from the market is unsubtle: the era of cheap money that underwrote speculative AI valuations is not returning soon, and companies must now demonstrate that their investments will produce cash, not just capability.
Inflation's stubborn grip
September's consumer-price data, released earlier this week, showed inflation running hotter than the Fed's 2% target despite eighteen months of elevated rates. The central bank faces an unenviable choice: hike again and risk tipping the economy into recession, or hold steady and watch inflation expectations become unanchored. Neither option is friendly to growth stocks trading at thirty or forty times earnings.
European equities followed Asia lower, with the Stoxx 600 technology index shedding more than 3% by midday in London. Fixed-income markets rallied as investors rotated into the relative safety of government bonds—a classic risk-off pattern that suggests this is more than a one-day tantrum.
Our take
The AI boom was never going to proceed in a straight line, and a correction was overdue. What matters now is whether this selloff marks a healthy repricing or the beginning of a deeper reassessment of how much society is willing to pay for generative intelligence. The companies building AI infrastructure are not frauds; their technology is real and transformative. But transformation takes time, and time costs money—especially when the Fed is no longer subsidizing patience. Investors who bought the dream at any price are learning that even revolutions must eventually produce a profit.