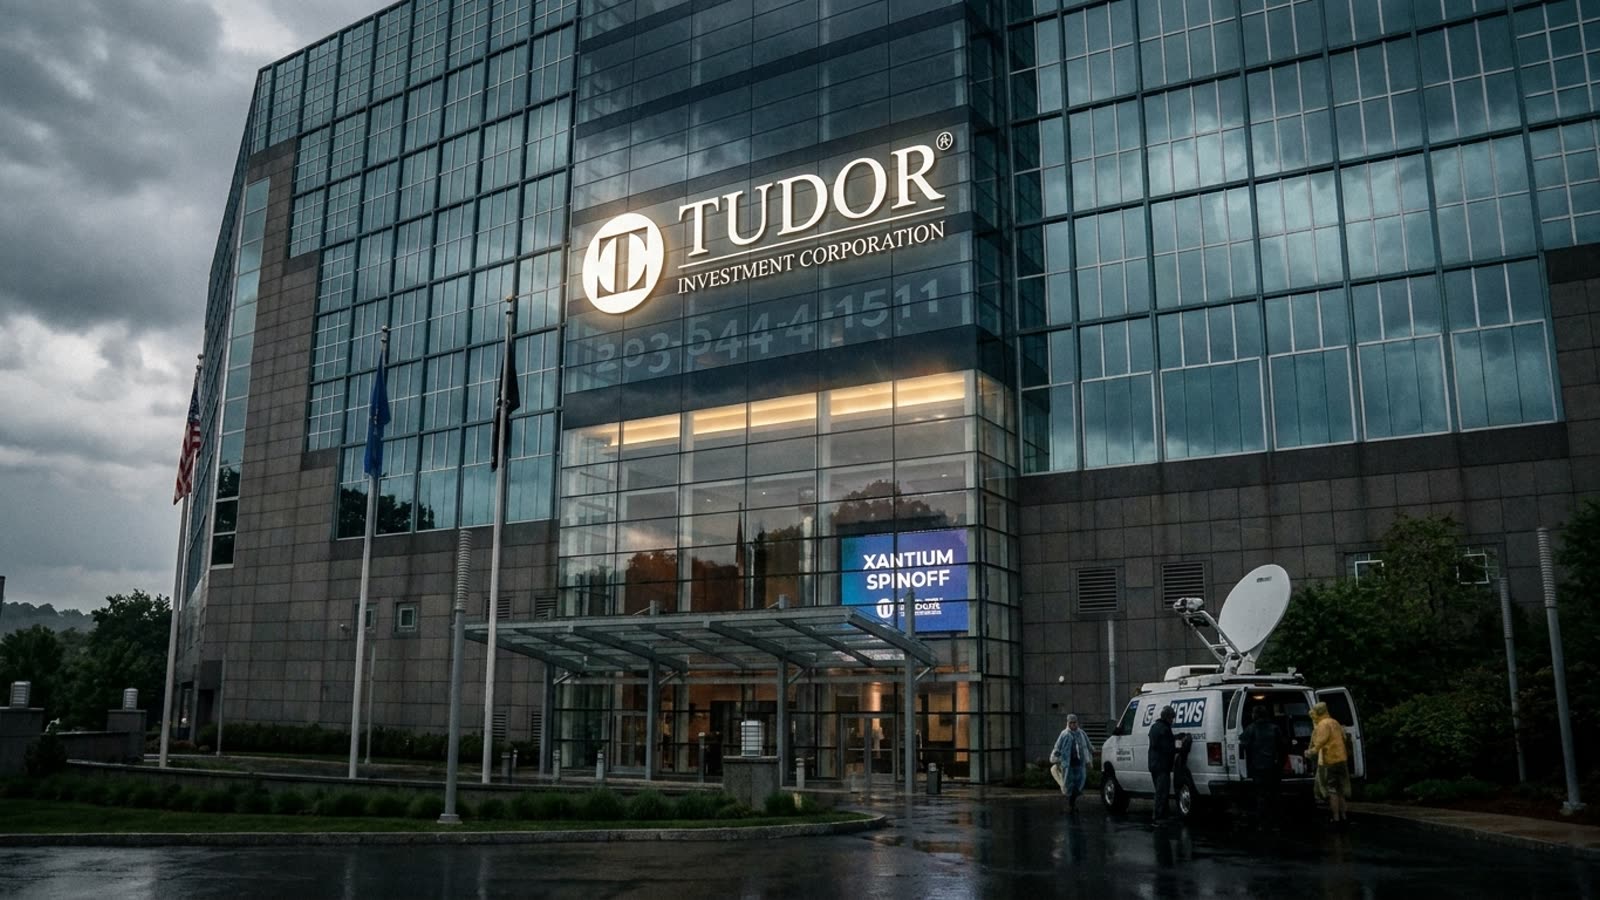
The most valuable asset at Tudor Investment Corp is walking out the door, and Paul Tudor Jones II is letting it happen. Xantium, the quantitative trading unit that has quietly become Tudor's profit engine, will separate next year in what sources describe as a $9 billion launch — the largest debut for a systematic hedge fund on record.
The spinoff is amicable, reportedly structured to preserve some economic ties between the two entities. But the symbolism is unmistakable. Jones, the legendary macro trader who called the 1987 crash and built a fortune on gut instinct and chart-reading, is ceding the future to the algorithm jockeys.
The quant ascendancy
Systematic strategies have been eating discretionary macro's lunch for a decade. The numbers are stark: quant funds now manage over $1.5 trillion globally, and their share of hedge fund assets has roughly doubled since 2015. The best talent — the physicists, mathematicians, and machine-learning engineers who can extract signal from noise — commands compensation that makes traditional portfolio managers look like middle management.
Xantium's team has reportedly delivered consistent double-digit returns by applying statistical arbitrage and machine-learning models to global markets. That consistency is precisely what macro trading cannot offer. Jones himself has had lean years; the broader macro cohort has struggled to justify fees in a world where central bank interventions and geopolitical shocks seem to defy pattern recognition.
Why Jones is letting go
There is a cold logic to the separation. Quant operations require massive technology infrastructure, continuous reinvestment in data and compute, and a culture of iterative model improvement that sits uneasily alongside the more improvisational ethos of macro trading. Keeping Xantium inside Tudor meant subsidizing two fundamentally different businesses under one roof.
The spinoff also reflects a generational transition. Jones, now in his early seventies, has been gradually stepping back from day-to-day trading. Xantium's leadership reportedly pushed for independence, seeking the autonomy to raise capital and recruit talent without the constraints of Tudor's legacy structure. A $9 billion launch gives them that runway.
What it means for the industry
Xantium's exit will intensify competition at the top of the quant pyramid. Citadel, Two Sigma, DE Shaw, and Renaissance Technologies already dominate, but the market for systematic alpha is not zero-sum in the way macro trading often is. More capital chasing statistical edges tends to compress returns over time, but it also accelerates innovation. The arms race in alternative data, execution speed, and model sophistication will only get hotter.
For Tudor, the question is existential: can a macro shop remain relevant when its most profitable unit has decamped? Jones retains a formidable reputation and deep pockets, but reputation does not compound.
Our take
This is not a betrayal; it is an acknowledgment. The hedge fund industry's romantic era — the Soros trades, the Druckenmiller calls, the Jones legend — is giving way to something colder and more scalable. Xantium's $9 billion debut is less a vote of confidence in any particular strategy than a verdict on where capital believes edge resides. The quants have won. The question now is whether anyone else can catch up.