Amazon's cloud division is no longer content to be merely enormous. During Thursday's earnings call, CEO Andy Jassy declared that AWS is on a trajectory to become the first business unit in history to generate one trillion dollars in annual revenue. The ambition is breathtaking; the price tag, less so.
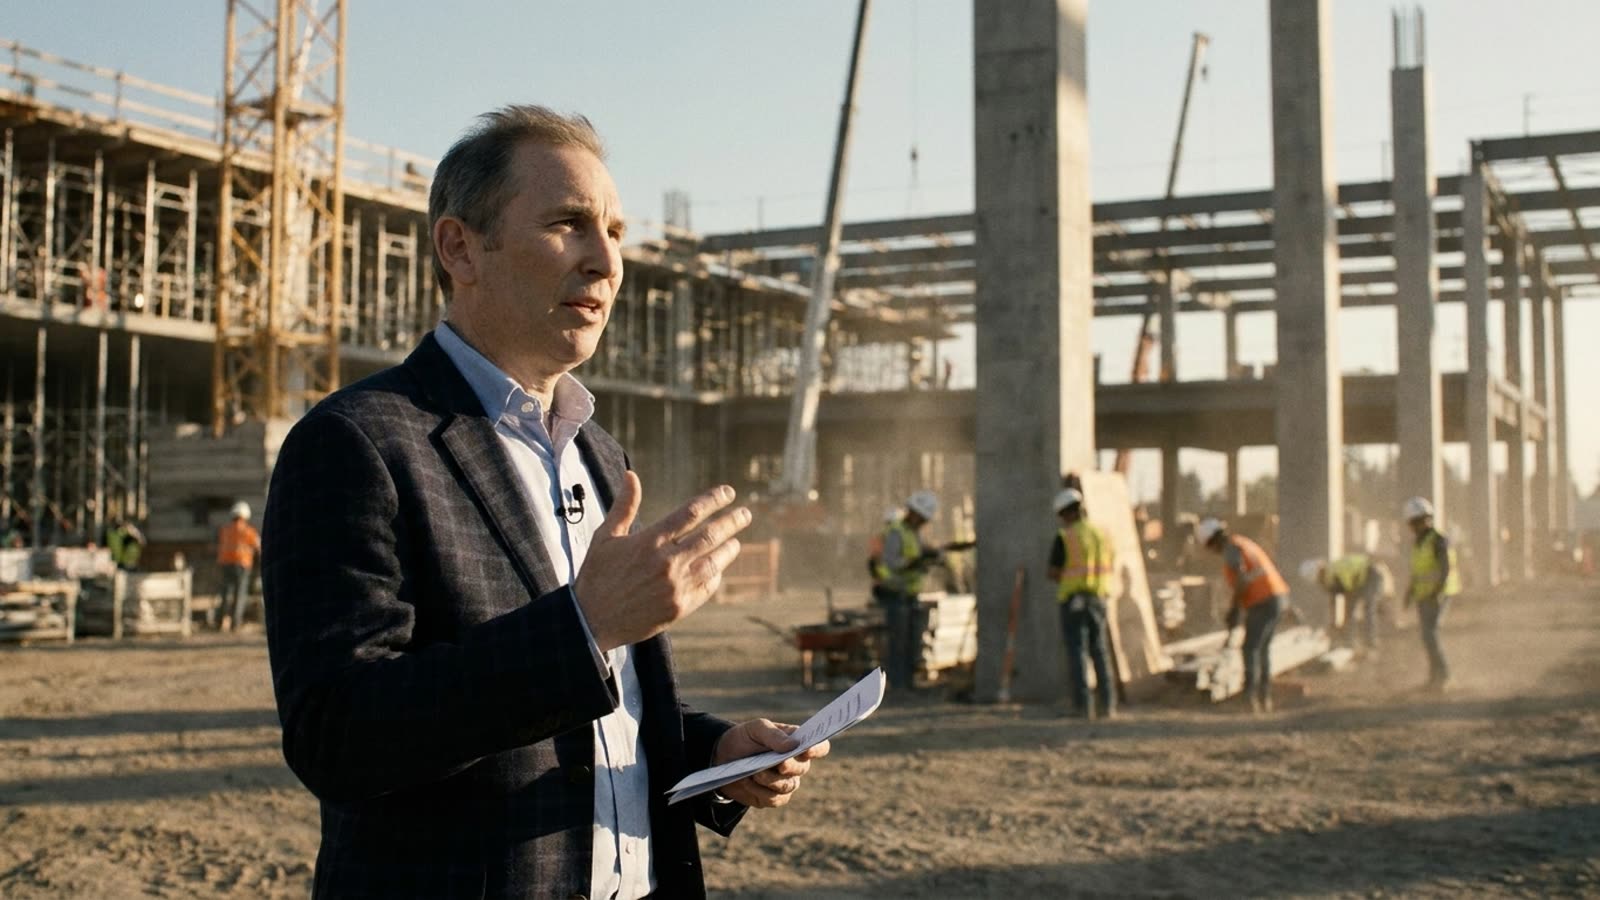
The company's capital expenditure plans for AI infrastructure have ballooned to levels that would have seemed absurd even two years ago. Amazon is building data centers at a pace that rivals small nations constructing entire power grids, all in service of a bet that enterprise AI workloads will migrate to the cloud faster than skeptics predict. Jassy's thesis is straightforward: whoever owns the picks and shovels of the AI gold rush wins the decade.
The capex conundrum
Wall Street's reaction to Amazon's guidance was notably cool, with shares sliding on a Christmas sales forecast that disappointed despite AWS's robust growth. The tension is structural. Investors have grown accustomed to cloud computing as a high-margin annuity business, but the AI infrastructure buildout is capital-intensive in ways that traditional server farms never were. Nvidia's GPU scarcity has eased somewhat, but the specialized cooling systems, power infrastructure, and real estate required for AI-scale computing remain expensive and slow to deploy.
Amazon is essentially asking shareholders to fund a second founding—a multi-year infrastructure bet that will suppress margins before it pays off. The company points to Prime Video's trajectory toward "tens of billions" in revenue as evidence that patient capital allocation works. But streaming and cloud computing operate on different physics; one is a content licensing game, the other a semiconductor arms race.
The competitive landscape
Microsoft and Google are running the same playbook, pouring billions into AI infrastructure while their core businesses generate the cash flow to sustain the spending. The difference is that Amazon's retail margins remain thinner than its hyperscaler rivals' software businesses, leaving less cushion for a prolonged investment cycle. If AI adoption slows or enterprises decide to build their own infrastructure—a trend already visible among the largest tech companies—AWS's trillion-dollar ambition could become a trillion-dollar albatross.
The timing is also awkward. Amazon's disappointing holiday guidance suggests that consumer spending remains fragile, and the company's advertising business, while growing, cannot yet compensate for retail softness. Jassy is betting that enterprise IT budgets will prove more resilient than consumer wallets, but that assumption has been wrong before.
Our take
Jassy's vision is probably correct in the long run—someone will build the infrastructure layer for enterprise AI, and Amazon has the scale, the customer relationships, and the operational discipline to be that someone. But "probably correct in the long run" is a difficult pitch to shareholders watching margins compress and competitors catch up. The trillion-dollar target is less a forecast than a statement of intent, a signal that Amazon will spend whatever it takes to own the AI cloud. Whether that spending creates value or merely defends market share is the question that will define Jassy's tenure.