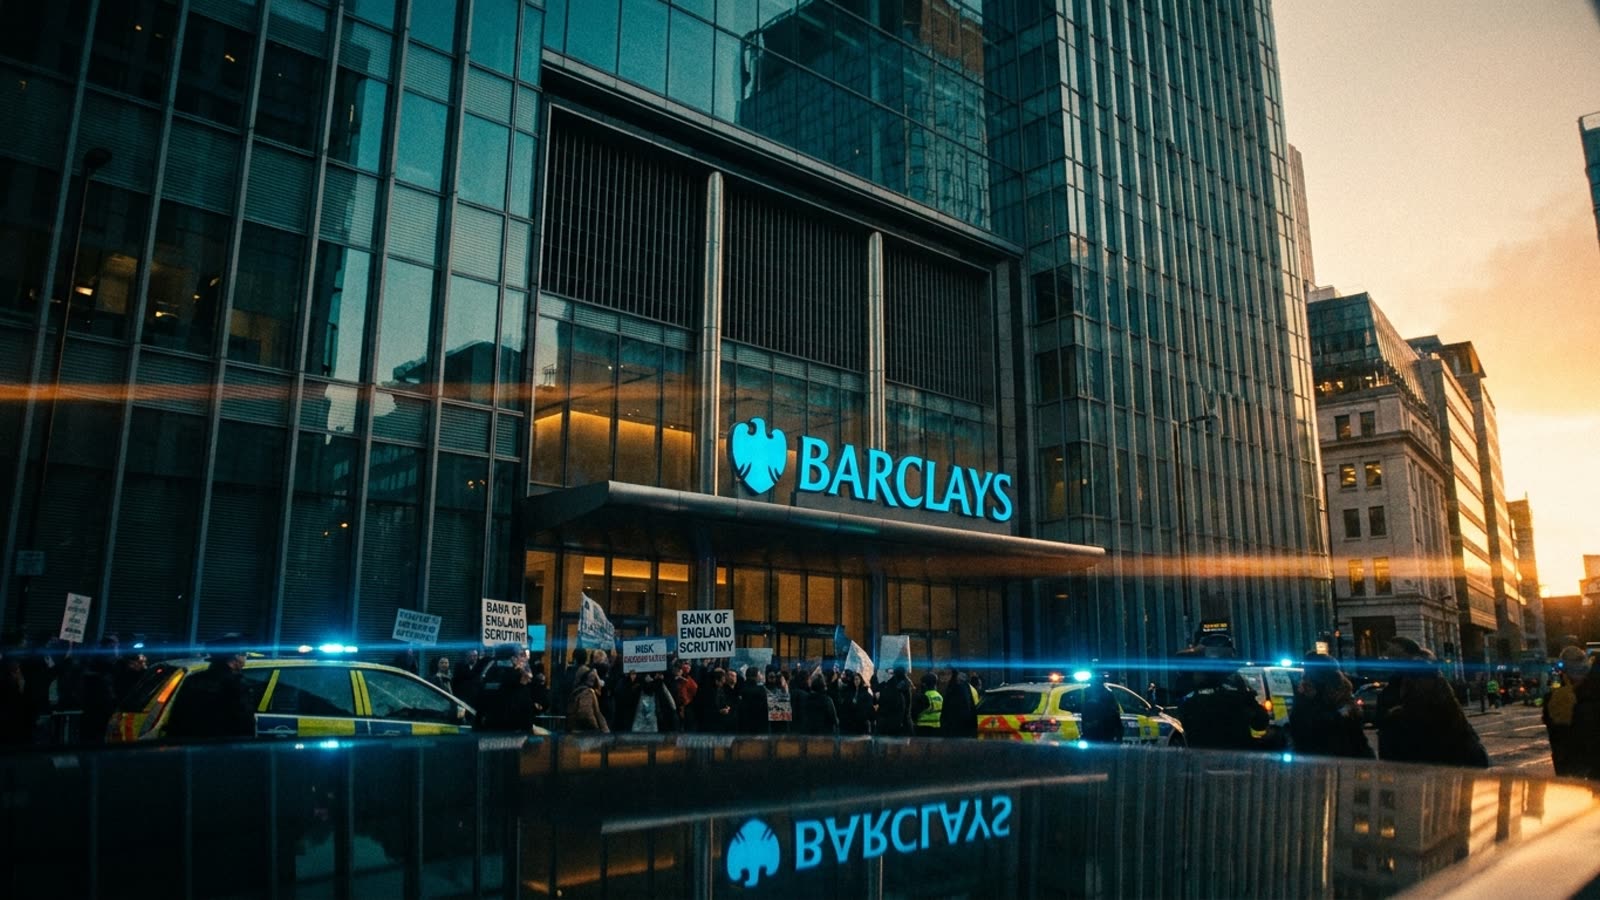
The Bank of England has opened an inquiry into whether Barclays traders misrepresented the risk profile of derivatives used to finance private credit loans, according to regulatory filings disclosed this morning. The complaint, lodged by an undisclosed party, alleges that the UK lender systematically understated exposure levels in a market that has swelled past $1.5 trillion globally.
Private credit—direct lending by non-bank institutions to mid-market companies—has become the fastest-growing corner of finance since 2020, fueled by institutional investors hunting yield and borrowers avoiding traditional bank scrutiny. What has received less attention is how regulated banks like Barclays have re-entered the game through the back door, using total return swaps and credit-linked notes to offer synthetic exposure without booking the underlying loans on balance sheet.
The derivatives detour
Barclays' model, common across several European and American banks, involves writing derivatives contracts that pay out based on the performance of private credit portfolios managed by funds like Apollo or Ares. The bank earns fees and spread income; the fund gets leverage or hedging capacity. On paper, the bank's capital requirement is lower than if it held the loans directly. In practice, if the underlying credits sour, the bank is on the hook for mark-to-market losses that can be abrupt and large.
The BoE complaint centers on whether Barclays' risk disclosures to regulators accurately reflected potential loss scenarios, particularly in a rising-rate environment where private equity-backed borrowers face refinancing stress. The inquiry comes weeks after the Basel Committee flagged synthetic credit exposures as an emerging supervisory blind spot. Barclays has not commented publicly; the investigation is in early stages.
Why this matters now
Private credit's appeal rests on the premise that it is uncorrelated with public markets and insulated from bank runs. But if major banks are quietly amassing derivative exposure to the same pool of borrowers, a credit event in private markets could ricochet back into the regulated banking system faster than supervisors expect. The BoE's move suggests regulators are belatedly mapping these linkages. Expect parallel inquiries at other institutions and renewed scrutiny of off-balance-sheet risk in the next round of stress tests.
Our take
Private credit was supposed to disintermediate banks, not give them a new way to hide leverage. If Barclays did understate risk, it is less a rogue-trader story than a structural flaw: derivatives let banks pretend they are out of the lending business while collecting all the same fees and tail risks. The BoE is right to ask hard questions now, before the next default cycle turns synthetic exposure into real losses.