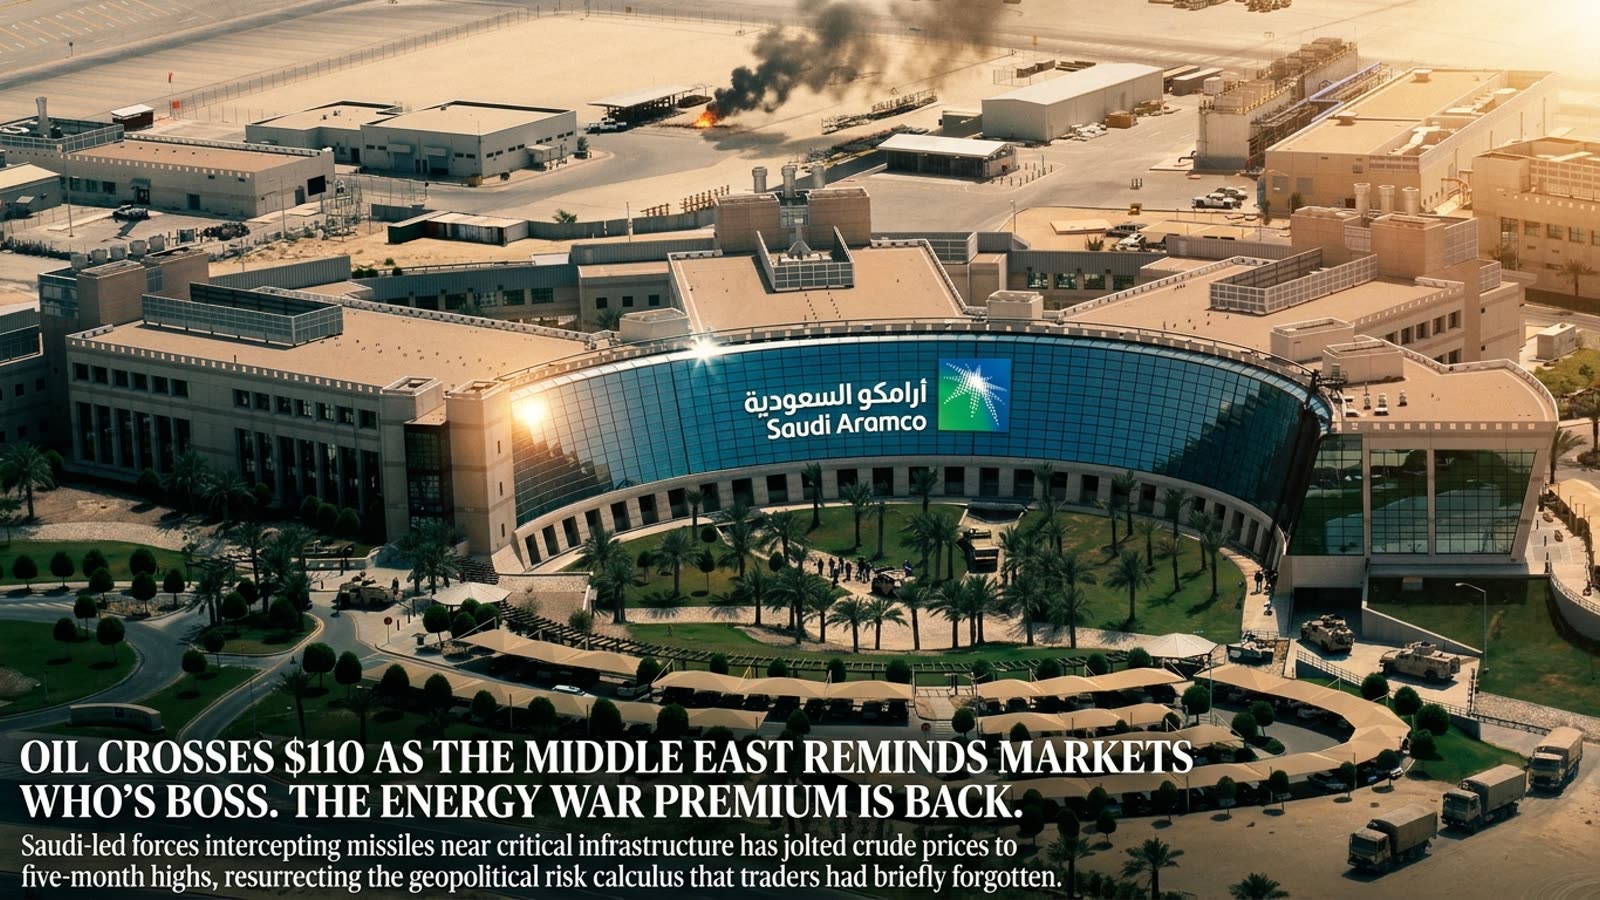
The comfortable assumption that oil markets had decoupled from Middle Eastern chaos lasted precisely as long as the chaos stayed theoretical. Brent crude's surge past $110 a barrel—its highest since May—arrived Friday on reports that Saudi Arabia-led forces intercepted and destroyed missiles targeting major energy infrastructure. The attack, whoever launched it, accomplished what months of diplomatic tension could not: it reminded every trading desk on earth that the world's most important commodity still flows through the world's most volatile region.
This is not a supply disruption story, not yet. Saudi production continues unimpeded, and no oil actually stopped flowing. But markets do not price barrels; they price probabilities. And the probability that a successful strike could take millions of barrels offline just became viscerally real to a generation of traders who had grown accustomed to treating geopolitical risk as background noise.
The infrastructure vulnerability no one wants to discuss
Saudi Arabia's energy infrastructure remains extraordinarily concentrated. The Abqaiq processing facility alone handles roughly seven million barrels per day—nearly 7% of global supply passing through a single site. The 2019 drone attack on Abqaiq temporarily knocked out half of Saudi production, and while defenses have improved since, the fundamental geometry has not. Critical chokepoints remain critical chokepoints.
Friday's interceptions suggest the defense systems worked. But the attacks' existence suggests adversaries believe those systems can be overwhelmed. This asymmetry—cheap drones and missiles versus expensive missile defense—defines the new energy security calculus. Each successful interception is also proof that someone is still trying.
Inflation implications arrive at an awkward moment
Central bankers, who had just begun congratulating themselves on taming inflation, are watching crude prices with renewed anxiety. Oil above $110 feeds directly into transportation costs, petrochemical prices, and ultimately consumer goods. The Federal Reserve's careful rate-cut choreography assumed energy prices would remain benign; that assumption now carries an asterisk.
For the European Central Bank, already navigating a fragile eurozone recovery, sustained oil price increases would force impossible choices between supporting growth and containing imported inflation. The Bank of Japan, meanwhile, watches the yen's weakness amplify every dollar of crude price increase into an even larger domestic burden.
The demand side hasn't gone away
Lost in the geopolitical drama is the underlying demand picture, which remains robust. Chinese crude imports have recovered from their summer lull, Indian consumption continues its structural climb, and American driving season may be over but industrial demand is not. The market was already tightening before missiles started flying.
OPEC+ production discipline, maintained despite internal grumbling, has kept supply constrained enough that any demand surprise—or supply scare—translates immediately into price. The cartel's strategy of defending prices over market share looks prescient in hindsight, though critics would note it also created the tight conditions that make geopolitical shocks so potent.
Our take
The return of the war premium is not a temporary phenomenon to be traded around; it is a structural feature of a world where energy infrastructure remains concentrated in unstable regions while the transition to alternatives proceeds at geological pace. Traders who spent the past year treating oil as a technical chart exercise just received an expensive reminder that commodities have geography, and geography has consequences. $110 may not hold, but the risk premium that put it there is not going anywhere.